Business Owners
Cash Balance Plans
The basics
What Is a Cash Balance Plan?
A cash balance plan is a type of retirement plan that combines the high contribution limits of a defined benefit plan with the flexibility and portability of a defined contribution plan. It provides a fixed, annual contribution to each participant’s account, which grows at a specified interest rate. At retirement, participants have the option to take their benefits as a lump sum or an annuity, offering greater flexibility in retirement planning.
Cash Balance Plans are a type of qualified retirement plan that can allow business owners and highly compensated employees (HCEs) to accelerate savings and maximize tax deductions. With the right demographics, contributions between $100,000 and $300,000 for owners or HCEs can be made. All contributions are fully deductible to the business for federal income tax purposes. Cash Balance Plans work best when combined with a 401(k) Plan. This provides for flexibility to the employees and employer in funding contributions, yet allows for maximum contributions.
Schedule A Call
The basics
How Do Cash Balance Plans Work?
- Hypothetical Account: participants have a hypothetical “account” that is credited with a pay credit (a percent of pay or flat dollar amount) and an interest credit (index-based).
- Retirement Benefits: are expressed in the form of a lump sum to participants and are easily portable to another group retirement plan or an IRA at retirement.
- Combo Plans: a Cash Balance Plan can be paired with a 401(k) Plan to allow for even higher savings.
- Federal Guarantee: benefits are usually insured by the Pension Benefit Guaranty Corporation (PBGC).
How we help business owners
Our Company
At FIS, we pride ourselves on providing top-notch financial advisory services tailored to meet the unique needs of our clients. Our dedicated team of experts specializes in cash balance plans, helping businesses and individuals secure their financial futures with confidence and ease.
How much can you contribute?
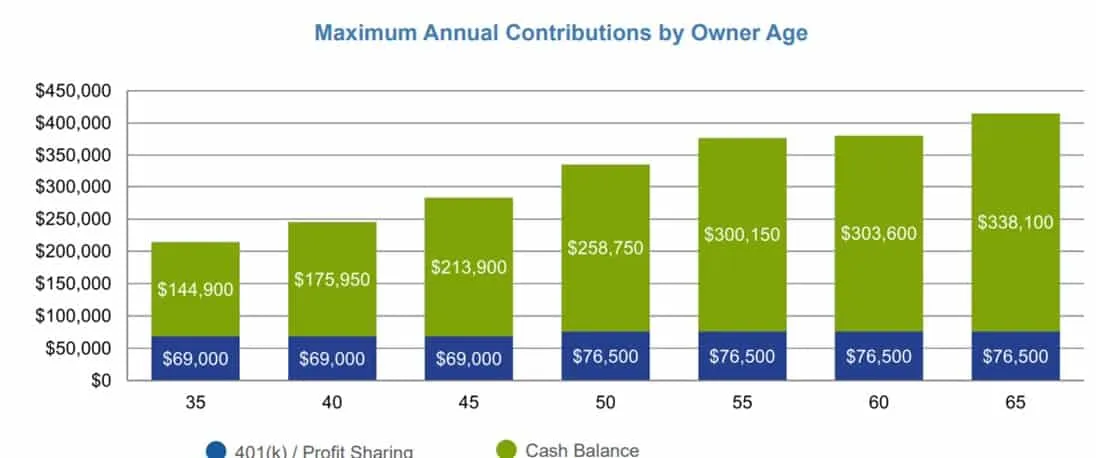
Maximum Annual Contributions By Owner Age
This chart highlights one of the most compelling advantages of a Cash Balance Plan: the ability to make significantly higher retirement contributions as you get older. Unlike 401(k)s, which have relatively low contribution limits, Cash Balance Plans allow business owners and professionals to contribute over $200,000 per year depending on age and income. This makes them a powerful tool for accelerating retirement savings—especially for those age 50 and older looking to catch up. The green bars represent the additional Cash Balance Plan contributions allowed on top of a 401(k)/Profit Sharing Plan.
What we’ll do
Our Services For Cash Balance Plans
Take the first step toward securing your financial future with a cash balance plan designed specifically for you. Contact FIS today to schedule a consultation and discover how our expertise can benefit your business and employees.
Schedule A Call-
Plan Design & Implementation
We work with you to design a cash balance plan that aligns with your business goals and objectives, ensuring a seamless implementation process.
-
Administration & Compliance
Our team handles all aspects of plan administration, including annual valuations, compliance testing, and government filings, to keep your plan in good standing.
-
Employee Communication & Education
We provide clear and concise communication materials to help your employees understand and maximize the benefits of their cash balance plan.
-
Ongoing Consulting
We offer continuous consulting services to address any questions or concerns you may have and to ensure your plan remains effective and compliant.
Real-world impact
See How Cash Balance Plans Work In Practice
Cash Balance Plans can be customized to fit a wide range of business types, income levels, and ownership structures. The following client profiles showcase how real business owners and professionals are using these plans to significantly increase their retirement savings and reduce taxable income, often contributing well beyond traditional plan limits.
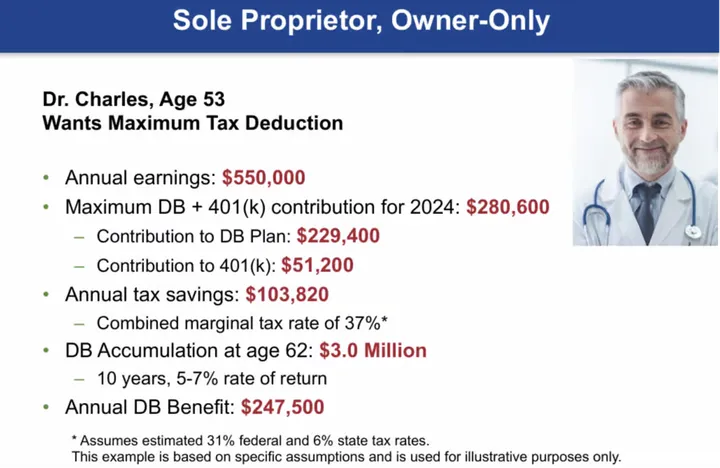
Example: Dr. Charles (Solo Proprietor, Owner-Only)
High-Earning Professionals Can Maximize Contributions
Meet Dr. Charles, a 53-year-old sole practitioner with no employees. Using a Cash Balance Plan alongside a 401(k)/Profit Sharing Plan, he was able to contribute over $280,000 toward his retirement in a single year. For high-income individuals like physicians, consultants, or attorneys operating alone or in partnerships, Cash Balance Plans provide a way to supercharge savings while reducing taxable income.
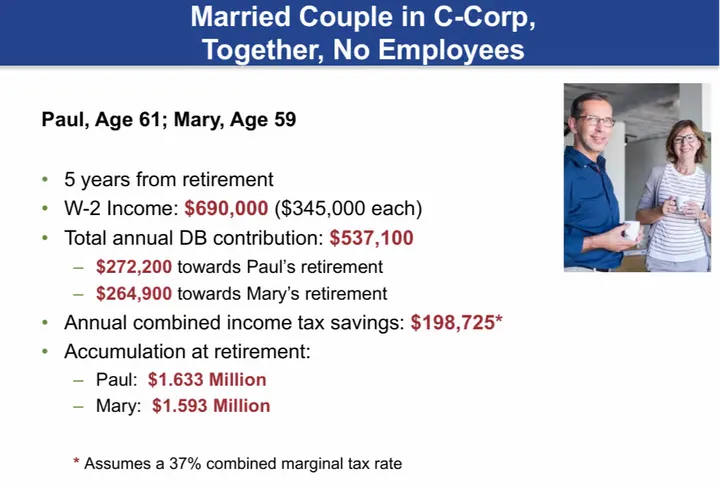
Example: Paul & Mary (Married Couple in C-Corp, No Employees)
Double the Savings for Spouse-Owned Businesses
Paul and Mary are a married couple, ages 61 and 59, who own a professional corporation together with no outside employees. Through a strategic plan design combining a Cash Balance Plan with 401(k)/Profit Sharing, they were able to contribute over $537,000 annually. This approach works especially well for small, family-run businesses where both spouses are active participants and looking to build retirement wealth rapidly.
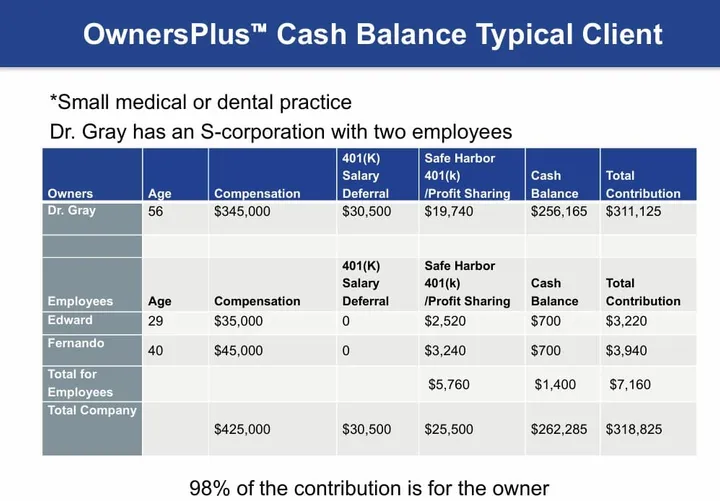
Example: OwnersPlus™ Typical Client Profile
Tailored for Small Practices and Owner-Operators
This example illustrates a typical client using the OwnersPlus™ Cash Balance Plan such as a small medical or dental practice with 1–5 employees. In this case, the business owner contributes the majority of total retirement funding, while still offering meaningful benefits to their team. With thoughtful plan design, over 98% of contributions go toward the owner’s retirement—making it a highly efficient and tax-savvy option for small business owners who want to reward themselves and their staff.
Is Cash Balance Right For Me?
Cash Balance Plans can be a fit for any company and are popular with professional firms like doctors, lawyers, and others who have the ability and desire to save more than is allowed under traditional plan arrangements and who have the steady income to comfortably make required contributions each year to this type of plan.
-
Seek Large Contributions
You seek contributions and tax deductions over $69k.
-
Profitable Business
Your business has strong profits and reliable cash flow.
-
Prepared to Contribute
You are prepared to contribute at least 5% – 7.5% of employees’ salaries annually.
-
Time to Catch Up
You have used cash to build your business and postponed retirement savings.
Cash Balance Plans are unique in how they work and how they are structured. Cash Balance Plans are a type of Defined Benefit Plan, but they offer some of the best features of Defined Benefit Plans and Defined Contribution Plans.
Schedule A CallWhy Choose Us?
At FIS, all of our financial services and investment strategies are rooted in our decades of experience that have prepared us to guide you through.
-
Expertise & Experience
With years of experience in the financial industry, our team has the knowledge and expertise to design and implement cash balance plans that meet the specific needs of your business and employees.
-
Customized Solutions
We understand that every client is unique. That’s why we take the time to get to know your business and tailor our services to provide the most effective cash balance plan solutions.
-
Comprehensive Support
From plan design and implementation to ongoing administration and compliance, we offer comprehensive support to ensure your cash balance plan runs smoothly and efficiently.
-
Client-Centered Approach
Our clients are at the heart of everything we do. We are committed to providing personalized service and building long-term relationships based on trust and mutual respect.
We Want To Hear From You
Contact us today to understand more about the white-glove service we provide to clients across the United States as their Fiduciary Fee-Only Investment Advisors.
Schedule A Meeting